Which States Sell Tax Lien Certificates?
It’s a common frustration for homeowners: those ever-present property tax bills. But what happens when those bills go unpaid? For local governments, it creates a funding gap, and to recover those much-needed revenues, they often turn to selling the outstanding debt. This process, known as a tax lien sale, isn't just a dry administrative procedure; it's an opportunity for savvy investors, and understanding which states participate can unlock a whole new world of investment potential. This guide will walk you through the landscape of states that sell tax lien certificates, explaining how they work and what you need to know to navigate this unique market.
Demystifying Tax Lien Certificates
Before we dive into specific states, let's get on the same page about what a tax lien certificate actually is. It might sound complex, but at its heart, it's a financial instrument stemming directly from unpaid property taxes. When a property owner doesn't pay their annual property taxes, the local government places a lien on that property. This lien essentially gives the government a legal claim to the property until the debt is satisfied.
What Exactly is a Property Tax Lien?
Think of a property tax lien as a silent promise, or perhaps a stern warning, stamped onto a piece of real estate. When property taxes go delinquent, usually after a specific due date and grace period, the local tax authority — be it a county, city, or even a smaller taxing district like a school board — will officially record a lien against that property. This lien is a super-priority claim, meaning it generally takes precedence over almost all other liens, including mortgages. It ensures that the government gets paid first when the property is sold or foreclosed upon. The sheer power of this lien is why the system works: homeowners, and especially mortgage lenders, have a strong incentive to clear these debts.
The local government needs funds to operate schools, maintain roads, provide emergency services, and much more. When property owners fall behind, these vital services are directly impacted. Rather than immediately foreclosing on a property, which can be a lengthy, expensive, and politically sensitive process, many jurisdictions opt to sell these tax liens to private investors. This allows the government to recover its owed taxes quickly, and it offers investors an opportunity to earn a return. You might want to understand more about What Happens If You Don't Pay Property Taxes?.
How Tax Lien Certificates Work
The sale of a tax lien certificate is essentially an auction. Investors bid on the right to pay off the delinquent property taxes, plus any associated penalties and fees, in exchange for the tax lien certificate. This certificate doesn't give you ownership of the property, at least not yet. Instead, it grants you the right to collect the original tax amount paid, plus a statutory interest rate, from the property owner.
The process typically involves a "redemption period," which is a timeframe set by state law during which the original property owner can pay back the taxes, penalties, and the interest owed to the tax lien certificate holder. If the property owner redeems the lien, the investor receives their original investment back plus the accrued interest. It's often a win-win: the county gets its money, the homeowner gets to keep their home by paying their taxes, and the investor earns a respectable rate of return.
However, if the property owner fails to redeem the lien by the end of the redemption period, the tax lien certificate holder can then initiate foreclosure proceedings to take ownership of the property. This is where the potential for significant profit lies, but it also introduces considerable risk and complexity. Understanding Tax Lien Sales & Certificates is crucial for anyone considering this type of investment.
The States That Embrace Tax Lien Sales
Not all states operate the same way when it comes to delinquent property taxes. The United States broadly follows two main systems for dealing with unpaid property taxes: the tax lien system and the tax deed system. Our focus here is on the tax lien states, which allow the sale of the lien itself.
Key Tax Lien States and Their Nuances
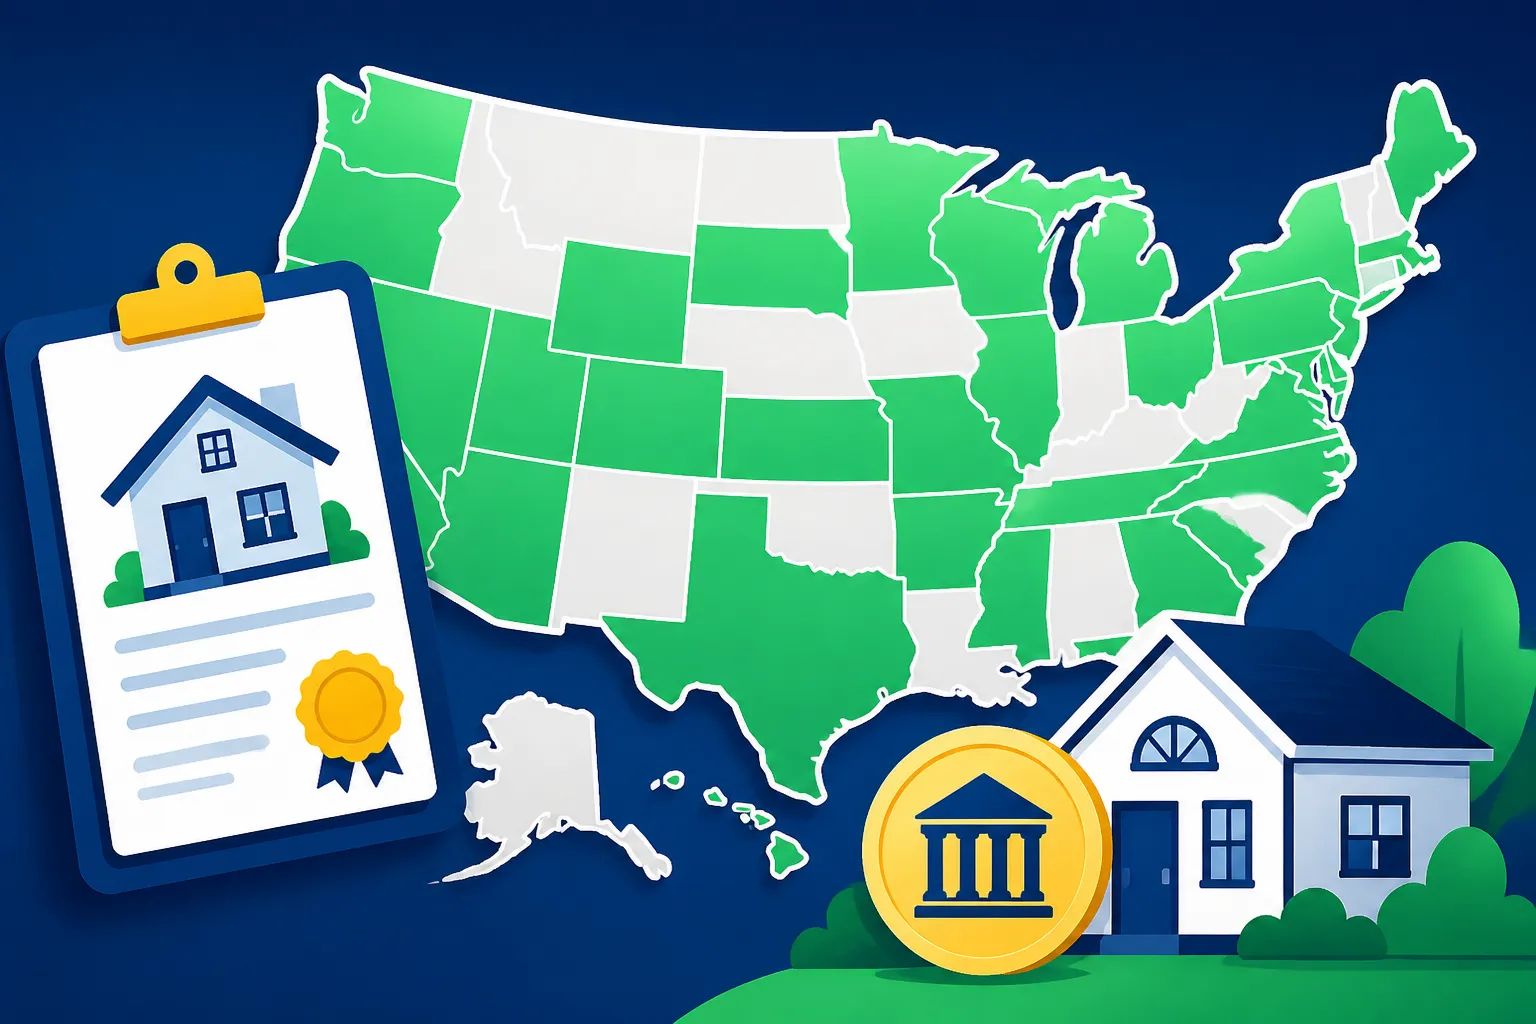
Roughly half of the states in the U.S. use some form of a tax lien sale system. These states essentially allow counties and municipalities to sell the right to collect delinquent property taxes to private investors. The interest rates, redemption periods, and auction formats can vary significantly from state to state, and even from county to county within a single state.
Here's a look at some of the most prominent tax lien states and what makes their systems unique:
- Arizona: Known for its robust tax lien market, Arizona often sees competitive bidding. Interest rates are set by statute but can be bid down by investors. The redemption period is typically three years, offering a good window for the property owner to catch up or for the investor to eventually pursue a tax deed.
- Florida: A very popular state for tax lien investing due to its high volume of available liens and generally favorable laws for investors. Florida uses a bid-down interest rate auction, where the lowest interest rate offered wins the lien. Redemption periods are usually two years. Florida also has a clear process for investors to apply for a tax deed if the lien is not redeemed.
- Illinois: This state has one of the longest redemption periods, often two years and six months for residential property, and sometimes even longer for others. Illinois tax lien auctions are typically bid-down interest rate sales, similar to Florida. Cook County, in particular, is a massive market.
- New Jersey: Offers some of the highest statutory interest rates on tax liens, up to 18% annually, which can make it very attractive. Auctions can be quite competitive, and the redemption period is typically two years. New Jersey also allows for a "premium" bid, where investors pay an amount above the taxes due, which is forfeited if the lien redeems. This often happens in competitive markets like Bergen County or Essex County.
- Maryland: The tax lien sale process in Maryland is often praised for its investor-friendly regulations. Redemption periods vary but are generally around six months, which is shorter than many other states, potentially leading to faster returns or quicker pathways to property ownership.
- Colorado: Similar to Arizona, Colorado offers a three-year redemption period. The interest rate is fixed annually based on the federal discount rate plus nine percentage points, providing a predictable return.
- Indiana: Known for relatively shorter redemption periods, sometimes as little as four months, depending on the specifics. This can accelerate the investment cycle but also requires swift action from investors if they need to pursue a tax deed.
- Ohio: Offers a variety of tax lien sales, including bulk sales to institutional investors and smaller, individual sales. Redemption periods are typically one year.
It's vital to research specific county rules, as processes can differ even within the same state. For example, while the state of Texas has a high property tax rate, it primarily operates under a tax deed system, not a tax lien certificate system for directly selling liens to investors, though tax sales do occur. This is an important distinction to make. Understanding the specifics for your target areas, like the Property Tax Due Dates by State, can give you an edge.
Here's a simplified comparison of a few key tax lien states:
| State | Typical Redemption Period | Interest Rate Mechanism | Unique Features |
|---|---|---|---|
| Arizona | 3 years | Bid-down interest rate | High volume, often competitive. |
| Florida | 2 years | Bid-down interest rate | Very active market, clear path to tax deed. |
| Illinois | 2 years 6 months (often) | Bid-down interest rate | Longer redemption period, large urban markets like Cook County. |
| New Jersey | 2 years | Fixed high statutory rate | Can bid a "premium" over the lien amount. |
| Maryland | 6 months (often) | Fixed statutory rate | Shorter redemption period, potentially faster investment cycle. |
| Colorado | 3 years | Fixed (discount rate + 9%) | Predictable interest rate, good for long-term hold. |
States Using Tax Deed Sales The Other Side of the Coin
While this article focuses on tax lien certificates, it’s equally important to understand the alternative: tax deed sales. Many states, including Texas, California (with some nuances), Georgia, and New York, primarily utilize the tax deed system. In these states, if property taxes remain unpaid, the taxing authority doesn't sell the lien itself. Instead, after a certain period and due process, they sell the property directly at a public auction to recover the delinquent taxes.
When you buy a property at a tax deed sale, you are generally acquiring the property outright, rather than just a lien. However, these sales usually come with no warranty, and the buyer assumes all risks regarding the property’s condition, potential hidden encumbrances, or even the possibility of a legal challenge to the sale. There's usually no redemption period after the tax deed sale, though some states might have a limited post-sale challenge period. This is a crucial distinction: with tax liens, you're earning interest and might get the property; with tax deeds, you're buying the property directly, often at a significant discount, but with higher risk. If you're looking into Tax Deed Sales Explained, it’s a whole different ballgame of due diligence.
Navigating the World of Tax Lien Investing
Venturing into tax lien investing can be an exciting journey, offering attractive returns and the potential to acquire real estate at a reduced cost. However, like any investment, it comes with its own set of challenges and considerations. It's not a "set it and forget it" strategy, and success hinges on thorough research and a deep understanding of local laws.
Potential Rewards and Inherent Risks
The allure of tax lien investing is often the promise of high, secure returns. Many states offer statutory interest rates that far exceed what you might find in traditional savings accounts or even some bonds. Imagine earning 8%, 12%, or even 18% on your money, backed by real estate! In many cases, these investments are considered relatively safe because the lien is secured by the property itself, and the primary goal of the property owner or their mortgage lender is almost always to redeem the lien. It's a powerful incentive to get paid.
Moreover, there's the long-shot potential of acquiring a property for the cost of the back taxes. If a lien isn't redeemed, and you successfully navigate the foreclosure process, you could end up owning a valuable piece of real estate for a fraction of its market value. This is the dream scenario that often attracts many to this niche.
However, the risks are just as real. The biggest risk is often the property itself. What if the property is dilapidated, contaminated with hazardous materials, or has other significant issues that make it undesirable? What if there are superior liens that somehow weren't cleared by the tax sale (though rare, it can happen, especially with federal liens)? The due diligence required before purchasing a tax lien is extensive. You need to investigate the property's condition, its market value, any other outstanding liens, and even the financial stability of the property owner if possible.
Another risk is simply not getting the property you desire. Most liens are redeemed, meaning you get your money back plus interest, but you don't acquire the property. While a good return is nice, if your ultimate goal was property acquisition, this can be a disappointment. Furthermore, the legal process of foreclosing on an unredeemed lien can be complex, time-consuming, and expensive, often requiring the assistance of an attorney. These legal costs can quickly eat into any potential profit if not managed carefully. Platforms like LendingTree often advise on the complexities of real estate and financing, reinforcing the need for careful financial planning when dealing with properties, whether for investment or homeownership.
Essential Steps for Aspiring Tax Lien Investors
Ready to dip your toes into the tax lien market? Here’s a breakdown of the essential steps you'll need to take to get started:
- Research State and Local Laws Thoroughly: This is paramount. As we've discussed, every state, and often every county, has its own rules regarding tax lien sales, interest rates, redemption periods, notification requirements, and the foreclosure process. You need to become an expert on the specific jurisdiction you're interested in. Look up the county tax collector's website, read their manuals for tax sales, and don't hesitate to call their office with questions. A deep dive into resources like Property Tax Liens Explained and How to Buy Tax Lien Certificates will be invaluable.
- Conduct Due Diligence on Properties: Never bid on a tax lien blindly. Before any auction, you should research every property on the list.
- Physical Inspection: Drive by the property. What condition is it in? Is it vacant? Is it even there? Are there any obvious issues?
- Title Search: While tax liens are super-priority, you need to understand the full title history. Are there any other liens? Federal liens, for example, might not be extinguished by a tax sale.
- Market Value: What is the property actually worth? Use online tools, consult a real estate agent, or look at comparable sales (comps) in the area. This helps you determine if the investment is worthwhile and what the potential equity is if you end up with the property.
- Environmental Concerns: Could the property have environmental contamination? This can be a huge liability.
- Property Owner Information: Sometimes, understanding the owner's situation can provide clues about the likelihood of redemption.
- Understand the Auction Process: Tax lien auctions are public and can take various forms:
- Bid-Down Interest Rate: Investors bid on the lowest interest rate they are willing to accept. The lowest bidder wins.
- Premium Bid: Investors bid an amount over the actual taxes due. This "premium" is lost if the lien is redeemed. The highest premium bidder wins.
- Rotation or Random Allocation: Less common, but some jurisdictions simply rotate the liens among registered investors or use a lottery system.
Attend a few auctions as an observer before you start bidding. This will give you a feel for the pace, the competition, and the specific procedures.
- Budget for Additional Costs: Your initial investment isn't just the cost of the tax lien. You'll need to account for:
- Subsequent Taxes: Often, you'll need to pay subsequent property taxes on the property to protect your lien, especially if the original owner continues to default.
- Foreclosure Costs: If the lien isn't redeemed, legal fees for foreclosure can be substantial, ranging from a few thousand dollars to much more, depending on the complexity and state laws.
- Property Maintenance/Rehabilitation: If you acquire the property, you'll likely incur costs to bring it up to marketable condition.
- Seek Professional Advice: Especially when starting out, consulting with an attorney specializing in real estate and tax law is highly recommended. They can help you understand the intricacies of the process and review your strategies. Financial management tools like Stessa, while typically used by landlords for managing rental properties, could become relevant if you acquire a property through an unredeemed tax lien and decide to hold it as an investment property. It helps track income, expenses, and overall portfolio performance, which would be crucial once you transition from a lien holder to a property owner.
Tax lien investing can be a rewarding path, but it requires diligent homework, patience, and a willingness to understand the legal and practical nuances involved.
Disclaimer
The information provided in this guide is for general informational purposes only and does not constitute financial, legal, or tax advice. Property tax laws and regulations are complex and vary significantly by jurisdiction. Always consult with a qualified legal or financial professional before making any investment decisions related to property tax liens or tax deeds. Investing in tax liens involves inherent risks, and there is no guarantee of return or property acquisition.