Property Tax Foreclosure Timeline
The unsettling thought of losing your home over something as seemingly routine as property taxes is a fear many homeowners secretly harbor. When those assessment notices and overdue bills start arriving, it's incredibly easy to feel a knot of anxiety tighten in your stomach, unsure of what each official-looking document means for your future. This comprehensive guide is designed to cut through that confusion, giving you a clear, empathetic look at the property tax foreclosure timeline, the crucial stages involved, and most importantly, what steps you can take along the way.
Understanding Property Tax Delinquency: The First Steps
Before any talk of foreclosure, there's a period of delinquency. This is when your property taxes become officially overdue. It's a critical phase, and understanding what happens here can make all the difference in preventing more severe consequences. Ignoring these initial notices is a common, yet dangerous, mistake that can lead to a cascade of financial and legal troubles.
Initial Penalties and Interest Accumulation
When that property tax bill's due date passes without payment, it doesn't just disappear. The first thing you'll likely notice is the addition of penalties and interest to your original tax amount. These aren't just minor fees; they can add up surprisingly fast, making an already challenging situation even tougher. Each state and even individual counties and municipalities have their own specific schedule for when taxes become delinquent and what penalties apply.
For instance, in Texas, property taxes typically become delinquent on February 1st of the year following the tax year for which they were assessed. If you don't pay by then, a penalty of 6% is usually tacked on, plus 1% interest for the first month. This can quickly escalate to a maximum penalty of 12% by June 1st, along with accrued interest. Similarly, in a state like Illinois, specifically Cook County, the first installment of property taxes is generally due in early March, and the second installment in early fall. Missing these can result in a 1.5% penalty per month on the unpaid amount. These penalties are designed to encourage timely payment, but for homeowners struggling, they often feel like an impossible hurdle, burying them deeper in debt. It’s vital to understand What Happens If You Don't Pay Property Taxes?, as the immediate consequences are usually financial.
Communication from the Taxing Authority
Once your taxes are delinquent, the taxing authority isn't just sitting back silently. You'll start receiving a series of official communications. These aren't usually gentle reminders; they're legal notices, often sent by certified mail, informing you of your overdue balance, the penalties incurred, and the potential next steps if payment isn't made. These notices can vary significantly in their tone and content, but they all carry the same underlying message: pay up, or face escalating action.
These communications might include a "Notice of Delinquency," a statement outlining the total amount due, including interest and penalties, and a firm deadline for payment before further action is taken. Some notices might even hint at the potential for a tax lien or tax deed sale, which can sound incredibly frightening. It's easy to shove these intimidating envelopes into a drawer and hope they go away, but that's precisely when you need to open them, read them carefully, and understand the deadlines they contain. This is the stage where you still have the most options and leverage to resolve the issue before it spirals out of control. Familiarizing yourself with the nuances of your local jurisdiction's Property Tax Due Dates by State can help you anticipate these communications and prevent them from becoming delinquent in the first place.
The Journey Towards Foreclosure: Key Milestones
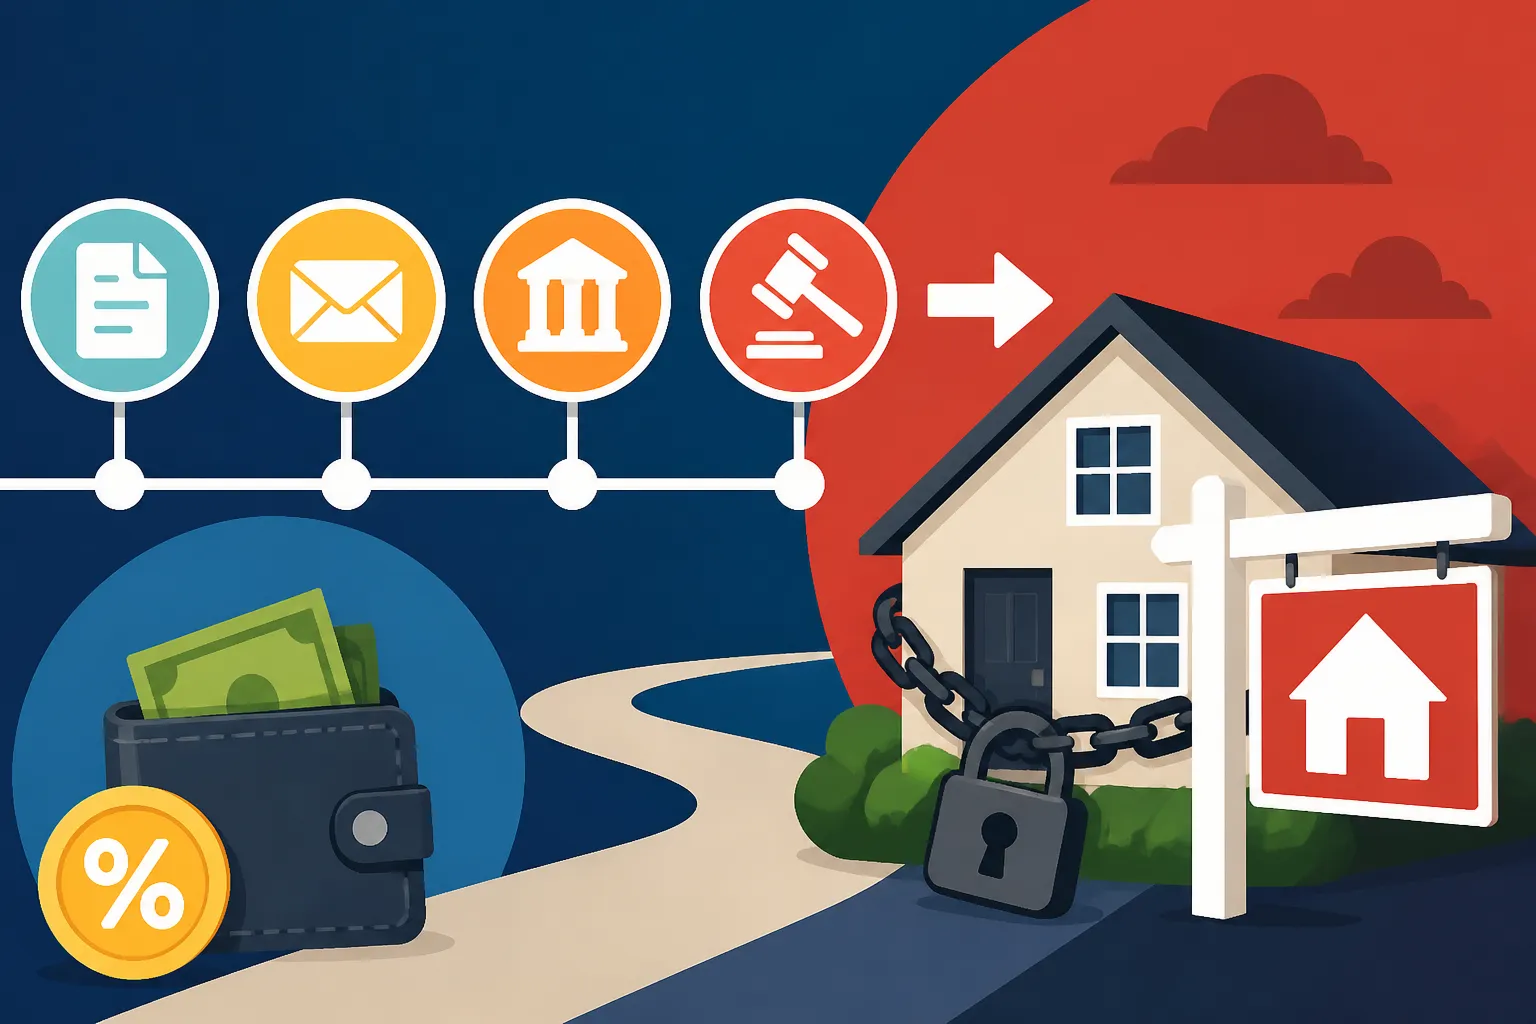
If delinquent taxes remain unpaid, the process moves into a more serious phase, eventually leading to foreclosure. This isn't usually an overnight event; it's a structured, legal process with several distinct milestones, each bringing the property closer to being sold to recover the unpaid taxes.
Formal Notice of Delinquency and Intent to Sell
After the initial period of penalties and interest, if no payment arrangement has been made, the taxing authority will issue a more formal and stern "Notice of Delinquency" or "Notice of Intent to Sell." This notice typically serves as a final warning before the county begins legal proceedings to sell the property or the tax lien on the property. This document is crucial because it often specifies the last date by which you can pay the outstanding taxes, interest, and penalties to avoid further legal action.
The specifics of this notice, including the timeline and what it mandates, are heavily dependent on state and local laws. For example, in some states, this notice might be published in a local newspaper as a public record, adding another layer of stress and public exposure to your financial difficulties. It’s not just a polite request; it’s a formal declaration that the county intends to exercise its right to collect the taxes, even if it means eventually taking possession of or selling your home. Missing this critical deadline can trigger the formal legal process that is difficult and costly to reverse.
Legal Action: The Foreclosure Petition or Lawsuit
When the final payment deadline from the notice of intent to sell passes without resolution, the taxing authority will initiate legal action. This usually involves filing a foreclosure petition or a lawsuit in court. The purpose of this legal filing is to obtain a court order allowing the county to sell your property (or the tax lien on it) to recover the unpaid taxes. You will be served with a summons and a copy of the complaint, meaning you are now officially involved in a legal proceeding.
This is where the process becomes even more intimidating. You might need to consult an attorney specializing in property law or tax issues, as navigating the court system can be complex and overwhelming. Depending on the state, this lawsuit might seek a "judgment of foreclosure and order of sale" for the property itself (common in tax deed states), or it might seek to sell a "tax lien" on the property (common in tax lien states). The difference, as we’ll explore shortly, is significant. This stage can involve court appearances, responses to legal filings, and negotiations with the taxing authority's legal counsel. Understanding the intricate details of a Property Tax Liens Explained or Tax Deed Sales Explained can help clarify what's at stake during this legal phase.
Judgment and Preparation for the Tax Sale
If the court rules in favor of the taxing authority – which it almost always will if the taxes are indeed unpaid and proper procedures have been followed – a judgment of foreclosure and order of sale will be issued. This legal document grants the county the power to proceed with selling your property. Once this judgment is obtained, the property is typically scheduled for a public auction, often referred to as a "tax sale" or "tax deed sale."
Before the sale, there's usually a period of advertising, where the property is publicly listed for auction, often in local newspapers or online government portals. This advertisement will include the property's address, the amount of delinquent taxes owed, and the date and time of the auction. For the homeowner, this stage can be particularly distressing, as the threat of losing their home becomes very real and public. Even at this point, some states allow for payment in full (including all accumulated taxes, penalties, interest, and legal fees) to stop the sale. However, the costs by now are significantly higher than the original tax bill. This is your last chance to intervene before the property is exposed to potential buyers looking for a bargain.
Two Paths to Foreclosure: Tax Lien vs. Tax Deed States
The path to property tax foreclosure isn't uniform across the United States. States generally follow one of two primary approaches: tax lien sales or tax deed sales. Understanding which type of state you're in is crucial, as it dictates the specific timeline, the rights of the homeowner, and what an investor actually buys at a tax sale.
How Tax Lien States Operate
In tax lien states, when property taxes become delinquent, the local government doesn't immediately sell the property itself. Instead, it sells the tax lien on the property to investors. A tax lien is essentially a claim against the property for the unpaid taxes, plus any penalties and interest. When an investor buys a tax lien certificate, they are essentially paying off the homeowner's delinquent taxes to the county. In return, they receive the right to collect the original tax amount plus a set interest rate from the homeowner.
The beauty of tax lien states, from a homeowner's perspective, is the redemption period. After the tax lien is sold, the homeowner typically has a period of time (which can range from one to three years, depending on the state) to "redeem" the property. To redeem, the homeowner must pay the investor the amount they paid for the lien, plus all accrued interest and any subsequent taxes paid by the investor. If the homeowner redeems, the investor's lien is removed, and the homeowner retains ownership. If the homeowner fails to redeem within the specified timeframe, the investor can then initiate a separate legal process to foreclose on the property and obtain the deed. States like Arizona, Florida, Illinois, and New Jersey are prominent examples of tax lien states. For instance, in New Jersey, homeowners generally have a two-year period to redeem after a tax lien sale.
How Tax Deed States Operate
In tax deed states, the process is more direct. If property taxes remain unpaid for a statutory period, the taxing authority moves to sell the property itself directly to recover the delinquent taxes. There's no separate "lien" sold first. At a tax deed sale, the highest bidder essentially buys the property outright, subject to specific conditions.
While the sale is more immediate, many tax deed states also include a redemption period, though it's often shorter than in tax lien states, sometimes ranging from a few months to a year or two. During this period, the original homeowner can still pay off the delinquent taxes, penalties, and interest, along with any costs incurred by the new buyer, to reclaim their property. If the property is not redeemed, the buyer receives a tax deed, which transfers ownership of the property directly to them. This can feel much more urgent and final for a homeowner, as the immediate consequence of non-payment is the potential loss of the home itself at auction. States like California, Texas, and Georgia are examples of tax deed states. The Florida Tax Lien & Tax Deed Process is a good example of how a state might manage these complex procedures.
Hybrid Models and Unique State Rules
It's also worth noting that some states employ "hybrid" models or have unique rules that blend elements of both tax lien and tax deed systems, or offer alternative collection methods. For example, some states might initially sell a tax lien but allow the county to directly sell the property via a tax deed if the lien isn't redeemed after a certain period, without requiring a separate investor-initiated foreclosure.
Other states might focus on what's called a "strict foreclosure" process for tax defaults, where a court simply declares that the property is forfeited to the county or municipality if taxes aren't paid by a certain date. The key takeaway is that the exact path your property tax delinquency takes will be deeply rooted in the specific laws of your state, county, and even city. It’s never a bad idea to contact your local tax assessor’s office or a qualified legal professional to understand the precise rules that apply to your situation. This nuance is why understanding specific local guidelines, such as those covered in Property Taxes: Texas vs California Compared, is so valuable.
The Critical Window: Property Tax Redemption Periods
The concept of a "redemption period" is a vital lifeline for homeowners facing property tax foreclosure. It's a legally defined timeframe during which you can reclaim your property, even after it's been sold at a tax sale, by paying off the delinquent taxes, penalties, and interest. This period is a final opportunity to prevent the permanent loss of your home.
Understanding the Redemption Right
The right of redemption is enshrined in the laws of many states to protect homeowners from immediately losing their property due to a tax delinquency. It acknowledges that life happens – unexpected job loss, medical emergencies, or other financial hardships can make paying property taxes impossible. This period provides a crucial window, often ranging from several months to a few years, giving the homeowner time to get their finances in order, seek assistance, or even sell the property themselves to pay off the debt and retain any equity.
To exercise the right of redemption, the homeowner must typically pay the full amount of delinquent taxes, all accumulated penalties and interest, any subsequent taxes paid by the lienholder or tax deed buyer, and often a redemption fee. This amount can be substantially higher than the original delinquent tax bill, reflecting the costs incurred by the county and the investor. However, for many, it's a small price to pay to save their home and prevent total loss. It's important to understand that if you fail to redeem within this period, your rights to the property are typically extinguished, and the new owner (either the tax lien investor who foreclosed or the tax deed buyer) will gain full, undisputed title. Diving deeper into Redemption Periods & Tax Foreclosure can provide a comprehensive overview.
Variations in State Redemption Timelines
The length of the redemption period is not universal; it varies significantly from state to state and even depends on the type of tax sale (lien vs. deed). For example:
- Texas: As a tax deed state, Texas typically has a relatively short redemption period. For homestead properties or agricultural land, the redemption period is two years. For other types of property, it's generally six months. This means you have a limited time to act after a tax sale.
- Florida: Florida is a tax lien state. When a tax certificate is sold, there's a two-year waiting period before the certificate holder can apply for a tax deed. During this time, the homeowner can redeem. Once the tax deed application is made, the homeowner has a limited time (often just a few weeks) before the tax deed sale to redeem.
- Illinois: As a tax lien state, Illinois offers a more generous redemption period. For most properties, it's generally two and a half years from the date the tax lien was sold. This extended period provides a significant cushion for homeowners to recover.
- New Jersey: Also a tax lien state, New Jersey generally provides a two-year redemption period after the tax lien is sold.
These examples highlight the critical importance of knowing your local laws. The moment you receive any official notice of delinquency or a pending tax sale, you must research the specific redemption period applicable to your property in your state. This information is usually available on your county tax collector's or assessor's website, or through legal counsel. Do not rely on general timelines, as a few months can make all the difference in saving your home.
Proactive Measures: Avoiding Foreclosure
The best way to deal with property tax foreclosure is to avoid it entirely. Even if you're already behind, there are often steps you can take to prevent the worst-case scenario. It requires proactive engagement, understanding your options, and sometimes, seeking external help.
Exploring Payment Plans and Deferral Programs
Many taxing authorities understand that homeowners can face temporary financial hardships. To prevent widespread foreclosures and maintain a stable tax base, they often offer various programs designed to help you catch up on delinquent taxes. One of the most common is a payment plan, where you can arrange to pay your overdue taxes, interest, and penalties in installments over a set period. This makes the large lump sum more manageable and demonstrates your commitment to resolving the debt.
Another valuable option, particularly for vulnerable populations, are property tax deferral programs. These programs allow eligible homeowners (often seniors, disabled individuals, or those with very low income) to postpone paying their property taxes until a later date, typically until the property is sold or transferred. The deferred taxes usually accrue interest but can provide critical relief in the short term. Programs like these exist in states such as Oregon, where eligible seniors and disabled persons can defer payment, and even Texas offers a limited deferral for homeowners over 65, which freezes their school tax payments. Always inquire with your local tax assessor's office about available Property Tax Installment & Deferral Plans or Property Tax Deferral Programs by State specific to your area.
Seeking Exemptions and Assistance Programs
Beyond payment plans, many states and local governments offer a variety of property tax exemptions and assistance programs that can reduce your tax burden, making it easier to stay current. These are often overlooked but can provide significant savings. Common exemptions include:
- Homestead Exemptions: These reduce the taxable value of your primary residence. Most states have some form of homestead exemption, which can lower your annual tax bill considerably. For example, in Florida, the standard homestead exemption can reduce the assessed value by up to $50,000, leading to substantial savings. Learn more about the Homestead Exemption: Complete State-by-State Guide.
- Senior Exemptions: Many states offer additional property tax breaks or freezes for homeowners over a certain age (e.g., 65 or 70), recognizing they are often on fixed incomes. The Senior & Over-65 Property Tax Exemptions and Freezes are crucial for many retirees.
- Veteran & Disability Exemptions: Veterans, especially those with disabilities, often qualify for significant property tax relief, up to 100% exemption in some cases. Likewise, non-veteran disabled homeowners may also be eligible for specific Property Tax Disability Exemptions.
- Circuit Breaker Programs: These are income-based programs that provide property tax relief to low-income homeowners, essentially capping the amount of income that goes towards property taxes. Missouri's "circuit breaker" tax credit is a well-known example.
It's crucial to proactively apply for these exemptions, as they are rarely automatically granted. Check with your county assessor's office for a comprehensive list of what you might qualify for. Also, consider reaching out to local non-profit organizations or housing counseling agencies, as they often have resources and programs to assist homeowners struggling with property taxes, including guidance on How to Lower Your Property Tax Assessment if you believe your home's value has been incorrectly appraised.
Professional Guidance and Financial Tools
When facing the complexity of delinquent property taxes, you don't have to navigate it alone. Seeking professional guidance can provide clarity and strategic solutions. A local real estate attorney specializing in tax matters can review your situation, explain your legal rights, and represent you in discussions with the taxing authority or in court. They can help you understand the nuances of a Property Tax Appeal Deadlines by State or whether your assessment is fair.
Financial advisors or credit counselors can also help you restructure your budget, explore loan options, or connect you with programs designed for financial distress. For homeowners looking to manage their property finances more effectively, tools like Stessa can be incredibly helpful. While primarily designed for rental property investors, Stessa offers robust features for tracking income, expenses, and property performance, which can give any homeowner a clearer picture of their overall financial health and help them budget for property taxes. For those considering refinancing or obtaining a personal loan to cover delinquent taxes, exploring options through platforms like LendingTree can provide a wide range of choices from various lenders, allowing you to compare rates and terms to find a viable solution. The goal is to be informed and proactive, leveraging all available resources to avoid foreclosure.
Life After the Sale: What Happens Next?
If all attempts to redeem the property fail and the redemption period expires, the outcome is the permanent loss of your home. While devastating, it’s important to understand the final administrative and legal steps that follow a completed property tax sale.
The Transfer of Ownership
Once the redemption period has officially passed, the investor who purchased the tax lien (and successfully foreclosed on it) or the buyer at a tax deed sale will receive a tax deed. This document is the legal instrument that transfers ownership of the property from the original homeowner to the new buyer. At this point, the former homeowner has no further legal claim to the property. The new owner can then record this deed with the county recorder's office, making their ownership public and official.
This transfer is often a deeply emotional and challenging period for the former homeowner, who must now come to terms with the loss of their property. It signifies the end of their legal rights to the home, even if they've lived there for decades and built up significant equity. The new owner is legally entitled to the property, and the former owner has effectively been dispossessed. This is the stark reality that the entire property tax collection process is designed to prevent, making the earlier proactive steps even more critical.
Surplus Funds and Eviction Procedures
In some cases, especially if the property sells for more than the outstanding taxes, penalties, interest, and administrative costs, there might be surplus funds. These are the funds remaining after all governmental and sale-related debts are paid. Depending on state law, the former homeowner may have a right to claim these surplus funds. However, this often requires a separate legal process to petition the court or county for the excess amount, and it’s not always straightforward. This is where legal counsel becomes essential, as the process for claiming surplus funds can be complex, and third parties sometimes attempt to claim these funds from uninformed former owners.
Once the new owner has the tax deed, they have the right to possess the property. If the former homeowner is still living there, the new owner will need to initiate eviction proceedings to legally remove them. This is a court-supervised process that can vary in length depending on state and local tenant laws. It often involves providing formal notice to vacate, followed by a court filing if the former homeowner does not leave voluntarily. While emotionally difficult, it's important for former homeowners to understand their rights during an eviction process, even if they no longer own the property. Knowing the proper legal procedures can help ensure a smoother, albeit painful, transition. The Supreme Court case Tyler v. Hennepin County, decided in 2023, highlighted issues around surplus equity, suggesting that governments may not be able to keep surplus funds without due process, further emphasizing the importance of understanding your rights to those funds.
Disclaimer
The information provided in this guide is for general informational purposes only and does not constitute legal, financial, or tax advice. Property tax laws and procedures vary significantly by state and local jurisdiction and are subject to change. Always consult with a qualified legal professional, financial advisor, or your local tax authority for advice tailored to your specific situation. Reliance on any information in this article is solely at your own risk.