How Tax Lien Foreclosure Works
The unsettling reality of falling behind on property taxes can quickly escalate from a missed payment to a full-blown crisis, threatening the very home you've worked so hard to build. Many homeowners find themselves caught off guard by the aggressive nature of property tax collection and the harsh consequences that can follow, including the dreaded tax lien foreclosure. This comprehensive guide will walk you through the intricate process of how tax lien foreclosure works, demystifying the steps from delinquency to potential loss of your property, and crucially, how you might prevent it.
Understanding the Basics of Property Tax Liens
Before diving into the complexities of foreclosure, it's essential to grasp what a property tax lien truly is and how it differs across various states. This foundational knowledge is key to understanding the subsequent stages of the collection process.
What Exactly is a Property Tax Lien?
At its heart, a property tax lien is a legal claim against your property by a governmental entity – usually your county or municipality – to secure payment of unpaid property taxes. Think of it as a silent alarm bell. When you don't pay your property taxes, the local government doesn't just forget about it. They place this lien on your home, making it clear that they have a right to your property if those taxes remain unpaid. This lien takes precedence over almost all other claims against your property, including mortgages. This superior position is a major reason why lenders often require property taxes to be paid through an escrow account, to protect their own investment.
Unlike other types of liens you might encounter, property tax liens are automatic. There's no need for a court judgment to establish them; they arise by operation of law simply because you own the property and haven't paid your dues. These liens typically accrue interest and penalties, making the original debt grow over time. The specifics of these penalties, the interest rates, and the duration before further action is taken can vary significantly depending on where you live. For a deeper dive into the concept, you might want to read our detailed article on Property Tax Liens Explained.
Tax Lien States vs. Tax Deed States
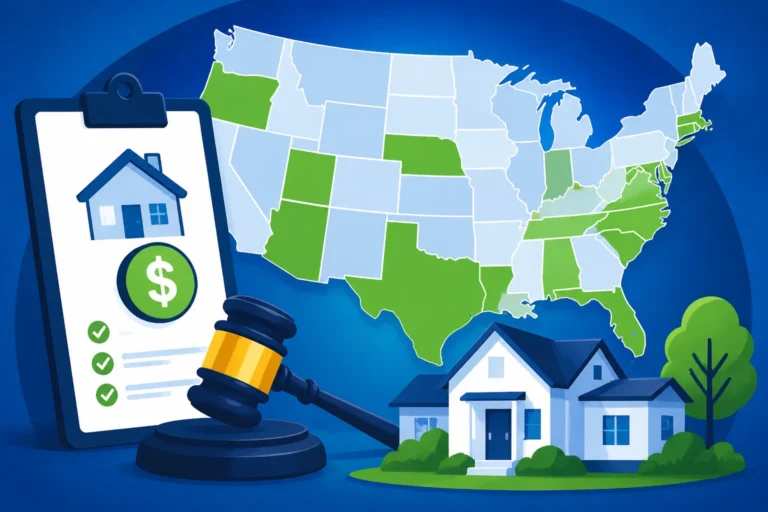
The path to potentially losing your home due to unpaid taxes largely depends on whether your state operates as a "tax lien" state or a "tax deed" state. This distinction is absolutely critical in understanding how tax lien foreclosure works.
In tax lien states, when property taxes go unpaid, the local government sells the tax lien certificate to private investors. This certificate represents the right to collect the delinquent taxes, plus interest and penalties. The investor essentially pays the overdue taxes to the county. The original homeowner then owes the investor, not the county. If the homeowner fails to pay the investor within a specified "redemption period," the investor can then initiate foreclosure proceedings to take ownership of the property. States like Arizona, Florida, and New Jersey are examples of tax lien states. The investor's goal is usually to earn a high rate of interest, but if not paid, they can pursue ownership.
Conversely, in tax deed states, the local government itself retains the lien. If the taxes remain unpaid after a certain period, the county can directly proceed to sell the property itself at a public auction, often referred to as a tax deed sale, to recover the back taxes. The highest bidder at a tax deed sale generally receives a tax deed, which transfers ownership of the property to them. In these states, there's often still a redemption period, but it might be shorter or structured differently than in tax lien states. California, Texas, and New York primarily operate as tax deed states. Understanding which system your state employs is fundamental because it dictates who you're dealing with (an investor or the county) and the precise legal steps involved in the process. You can find more comprehensive information on this topic in our article Tax Lien States vs Tax Deed States.
The Path from Delinquency to Tax Lien Sale
No one wants to fall behind on their property taxes, but life happens. Understanding the timeline from a missed payment to a tax lien sale can help you anticipate issues and potentially intervene before things get out of hand.
Falling Behind: Delinquent Property Taxes
The moment your property tax bill due date passes without payment, your taxes become delinquent. It's not an immediate catastrophe, but it's the first step down a slippery slope. Local tax authorities typically provide a grace period, but after that, penalties and interest begin to accrue. These charges can add up quickly, sometimes at surprisingly high rates, making it harder to catch up.
For example, in many jurisdictions, if your property taxes are due on January 31st and you haven't paid by February 1st, you might immediately incur a penalty, say, 5% of the unpaid amount, plus a monthly interest rate of 1% or more. These rates can be significantly higher than typical loan interest rates. The longer the taxes remain unpaid, the larger your total debt becomes, making it increasingly challenging for homeowners already struggling financially. It's crucial to be aware of your local Property Tax Due Dates by State and the specific penalties for late payment in your area. Ignoring these initial notices is a common mistake that allows a manageable problem to snowball into a much larger one.
The County's Collection Process and Lien Creation
Once your taxes are delinquent, the county tax assessor-collector's office or treasury department won't just sit idly by. They have a vested interest in collecting these funds, as they support essential local services like schools, fire departments, and roads. Their collection process typically involves a series of notices and warnings.
Initially, you'll receive polite reminders, perhaps a second or third notice, indicating the overdue amount, accumulated penalties, and potential next steps. If payment isn't received after these warnings, the county will formalize the lien on your property. This might involve recording the lien in the county land records, making it a public record. This official recording serves as a formal declaration that the property has an outstanding tax debt, and it attaches to the property itself, not just the owner. This is why if you sell your home, any outstanding property tax liens must be satisfied before the sale can close. Mortgage lenders, title companies, and potential buyers all check for these liens as part of their due diligence. This formal lien creation is a precursor to more severe collection actions, including the eventual tax lien sale in tax lien states or a tax deed sale in tax deed states.
The Tax Lien Sale: How Investors Get Involved
In states that follow the tax lien model, if the delinquent taxes, penalties, and interest remain unpaid for a statutory period (which can range from a few months to a few years), the county will put the tax lien up for sale. This is a public auction where private investors bid on the right to pay off the delinquent taxes in exchange for the tax lien certificate. These sales are often highly competitive, as tax lien certificates can offer attractive, legally mandated interest rates to investors.
During a tax lien sale, investors aren't buying your property directly; they're buying the right to collect your outstanding tax debt, plus a specified interest rate set by state law. For instance, in Florida, tax liens can accrue interest at rates up to 18% per year. The investor who bids the lowest interest rate or, in some cases, pays a premium over the lien amount, wins the certificate. Once an investor purchases the tax lien certificate, the homeowner now owes the delinquent amount, plus interest, to this private investor rather than the county. This shifts the dynamic significantly, as investors are often more aggressive in pursuing payment or, failing that, initiating the foreclosure process. You can learn more about this process and the opportunities for investors in our guide on Tax Lien Sales & Certificates.
How Tax Lien Foreclosure Proceedings Unfold
When a tax lien certificate remains unpaid by the homeowner, the investor (or the county in tax deed states) can move to "foreclose" on the lien, which ultimately means taking ownership of the property. This process is complex and governed by strict legal procedures.
Initiating the Foreclosure Process
The initiation of a tax lien foreclosure doesn't happen overnight. It typically begins only after a statutorily defined redemption period has passed and the homeowner has failed to pay the tax lien investor (or the county) the outstanding amount. The length of this redemption period varies widely by state, often ranging from one to three years, but sometimes as little as six months or as much as four years, depending on the property type and state laws.
Once this period expires without redemption, the tax lien investor, now holding the expired tax lien certificate, must typically file a lawsuit in civil court to officially foreclose on the property. This legal action is similar in some ways to a mortgage foreclosure, aiming to extinguish the homeowner's ownership rights and any other subordinate liens on the property. The investor's attorney will conduct a title search to identify all parties with an interest in the property (like mortgage lenders or other lienholders) who must be named in the lawsuit. This is a crucial step because failure to notify all interested parties can invalidate the foreclosure.
Notice Requirements and Due Process
Due process is a cornerstone of American law, ensuring that individuals receive fair treatment and proper notice before their property rights are impacted. In tax lien foreclosure, this translates into stringent notice requirements. The homeowner, and all other parties with a recorded interest in the property, must receive formal legal notification of the impending foreclosure action. This isn't just a casual letter; it's typically a summons and complaint served personally or through certified mail.
These notices explain that a lawsuit has been filed, detail the outstanding tax debt, and inform the homeowner of their right to respond in court. The purpose is to give the homeowner every opportunity to defend their rights, either by paying the delinquent taxes or challenging the validity of the lien or the foreclosure process itself. Mortgage lenders, for example, will also receive notice and often step in to pay the delinquent taxes to protect their primary lien, then add that cost to the homeowner's mortgage balance. Strict adherence to these notice procedures is essential; any significant deviation can be grounds for challenging the legitimacy of the tax lien foreclosure later on.
The Role of the Courts (or Administrative Bodies)
In most tax lien foreclosure scenarios, the courts play a central role. Once the lawsuit is filed and all parties have been properly notified, the case proceeds through the judicial system. The homeowner typically has a limited time to respond to the lawsuit, usually 20-30 days. If they fail to respond, the court can issue a default judgment, granting the investor the right to foreclose.
If the homeowner does respond, they may argue against the validity of the tax lien (e.g., the taxes were paid, the assessment was incorrect, or proper notice wasn't given). Such arguments are rare but can delay or even stop the foreclosure if proven valid. Assuming the lien is valid and no defense is successfully mounted, the court will typically issue a judgment of foreclosure. This judgment orders the sale of the property to satisfy the tax debt. In some states, particularly those operating under a tax deed system or with streamlined administrative processes, the foreclosure might not involve a full judicial lawsuit but rather an administrative proceeding through the tax collector's office. However, even these administrative processes usually have provisions for due process and opportunities for the homeowner to be heard.
The Redemption Period: Your Chance to Reclaim
For many homeowners facing tax lien foreclosure, the redemption period is the last, best chance to save their property. It's a critical window of opportunity that all property owners should understand.
Understanding the Statutory Redemption Period
The redemption period is a specific timeframe, legally defined by state statute, during which a delinquent property owner can "redeem" their property by paying off the outstanding tax lien, including all accrued interest, penalties, and the investor's legal costs incurred during the foreclosure process. This period is a protective measure for homeowners, providing a final chance to recover their property even after the tax lien has been sold or a foreclosure judgment has been issued.
The length of the redemption period varies significantly. For instance, in states like Florida, the redemption period is typically two years from April 1st of the year the tax lien certificate was issued. In other states like Texas, it can be as short as six months after the tax deed sale for homesteads and agricultural land, or two years for other property types. The specific duration can depend not only on the state but sometimes on the type of property (e.g., homestead vs. investment property) or even the circumstances of the tax delinquency. It's imperative for homeowners to identify the precise redemption period applicable to their situation, as missing this deadline can mean permanent loss of ownership. For a comprehensive look at these vital timelines, refer to our article on Redemption Periods & Tax Foreclosure.
Calculating Redemption Costs and Interest
Redeeming your property isn't as simple as just paying the original tax bill. The cost to redeem can be significantly higher due to the accumulation of interest, penalties, and legal fees. When an investor purchases a tax lien certificate, they do so with the expectation of a return on their investment. This return comes in the form of interest, which can be quite high, sometimes up to 18-25% annually, depending on state law.
Beyond the principal amount of the delinquent taxes and the accrued interest, the homeowner will also be responsible for any penalties imposed by the taxing authority, administrative fees, and crucially, all reasonable legal costs incurred by the tax lien investor during the foreclosure process. This includes attorney fees, court costs, title search expenses, and the cost of serving notices. It's a complex calculation, and the exact redemption amount will typically be provided by the tax collector's office or the investor's attorney upon request. Homeowners often find themselves in a difficult position where the redemption cost has ballooned beyond their immediate ability to pay.
Here's a simplified table comparing redemption periods and interest rates in a few representative states:
| State | Tax System | Typical Redemption Period | Statutory Interest Rate (Max/Common) | Notes |
|---|---|---|---|---|
| Arizona | Tax Lien | 3 years after the sale | 16% annually | Investor can take deed after redemption expires. |
| Florida | Tax Lien | 2 years from April 1st of issue | 18% annually | Investor applies for tax deed after 2 years. |
| New Jersey | Tax Lien | 2 years after sale | Up to 18% (premium dependent) | Judicial foreclosure required by investor. |
| Illinois | Tax Lien | 2.5 years (residential) | 18% every 6 months (36% annually) | Very high interest for investors. |
| Texas | Tax Deed | 6 months (homestead/ag) | 25% (year 1), 50% (year 2) | After tax deed sale; higher for longer period. |
| California | Tax Deed | 5 years of delinquency | 1.5% per month (18% annually) | Long redemption, but county takes direct action. |
Note: These are general guidelines; specific rules can vary by county and circumstance. Always verify with local tax authorities or legal counsel.
Exercising Your Right to Redeem
To exercise your right to redeem, you must pay the full redemption amount to the appropriate party, typically the tax collector's office, who will then disburse the funds to the investor. This payment effectively "buys back" the tax lien, clearing the claim against your property and preventing the investor from taking ownership. Once redeemed, the tax lien certificate is cancelled, and your property is no longer under threat from that specific delinquent tax amount.
It's crucial to act quickly and accurately. If you intend to redeem, contact the county tax office or the investor's legal representative as soon as possible to get an exact redemption figure. You'll need to confirm the payment method accepted (cashier's check, money order, wire transfer, etc.) and the precise deadline. Many homeowners facing this situation seek property tax loans or explore options like personal loans from institutions like LendingTree, though these should be carefully considered due to interest rates. In some extreme cases, a quick sale of the property might be the only way to generate funds for redemption, allowing the owner to salvage some equity rather than losing everything.
What Happens After Foreclosure: Tax Deed Sales and Investor Ownership
If the redemption period passes and the homeowner fails to pay the outstanding amounts, the property moves into the final stages of the tax collection process, often leading to a complete loss of ownership.
When Redemption Fails: The Tax Deed Sale
When the redemption period expires without the homeowner paying the investor (in tax lien states) or the county (in tax deed states), the next step is typically a tax deed sale. In tax lien states, the investor who holds the expired tax lien certificate can then apply to the county for a tax deed. This essentially transfers the property's title from the original homeowner to the investor. However, this isn't always automatic and may still require a judicial process to "quiet title," ensuring that all previous claims on the property are legally extinguished and the investor receives a clear title.
In tax deed states, once the redemption period has passed, the county itself conducts a public auction to sell the property directly to the highest bidder. This is a crucial distinction: here, the county is selling the property, not just the lien. The proceeds from the sale are used to pay off the delinquent taxes, penalties, interest, and administrative costs. Any remaining surplus funds may be returned to the former homeowner, but this is highly variable and often requires the former owner to proactively claim these funds, which can be a complex legal process itself. Losing your home in this manner is a devastating blow, underscoring the importance of addressing delinquent taxes early. More details on this can be found in our guide on Tax Deed Sales Explained.
Receiving a Clear Title: The Investor's Perspective
From an investor's standpoint, the ultimate goal of a tax lien certificate purchase or a tax deed sale bid is to acquire a property free and clear of most prior encumbrances, including mortgages. This is one of the most attractive aspects of tax-defaulted property investing. Generally, a properly executed tax deed will extinguish all prior liens, except for a few specific types, such as federal tax liens or environmental liens, depending on state law. This "super priority" of property tax liens means that a tax deed often conveys a fresh, unencumbered title to the new owner.
However, obtaining a truly "clear" title isn't always straightforward. Investors often need to perform an additional legal procedure called a "quiet title" action. This is a lawsuit filed by the new owner to formally establish their ownership against any potential claims from previous owners, mortgage lenders, or other lienholders. While the tax deed itself provides strong evidence of ownership, a quiet title action provides a judicial decree that definitively clears the title, making it marketable and insurable by title insurance companies. This step adds to the investor's costs but secures their investment fully.
The Impact on Homeowners: Losing Your Property
For the original homeowner, the expiration of the redemption period and the subsequent issuance of a tax deed is the final, heartbreaking step in losing their property. All ownership rights are extinguished, and they no longer have any claim to the home. This loss can be particularly devastating if the home had substantial equity, as the amount received from a tax deed sale might only cover the back taxes and fees, leaving little or no surplus for the former owner, as mentioned earlier.
The emotional and financial impact can be immense. Not only do homeowners lose their primary residence, but their credit score can also take a significant hit, making it harder to secure future housing or loans. This situation highlights the harsh reality of property taxes: while they fund vital public services, their non-payment carries severe consequences that can lead to home displacement. It serves as a stark reminder that property tax obligations are a fundamental and unavoidable aspect of homeownership.
Preventing Tax Lien Foreclosure and Finding Help
The best way to deal with tax lien foreclosure is to avoid it entirely. There are proactive steps and resources available to help homeowners manage their property tax obligations, even when facing financial hardship.
Proactive Steps to Avoid Delinquency
Staying on top of your property tax payments is paramount. Here are some proactive strategies:
- Budgeting and Savings: Integrate property taxes into your monthly budget. Even if you pay annually or semi-annually, set aside a portion of the payment each month into a dedicated savings account. This way, the lump sum isn't a shock when it's due. Financial management tools can help track these expenses.
- Escrow Accounts: If you have a mortgage, your lender likely requires an escrow account. This means a portion of your monthly mortgage payment goes into an account managed by the lender, who then pays your property taxes (and insurance) on your behalf. While it adds to your monthly housing cost, it effectively automates tax payments and ensures they are never missed. For those without an escrow account, consider setting one up yourself, perhaps through your bank, by contributing a prorated amount monthly.
- Understanding Your Bill: Don't just pay your bill without understanding it. Review your How to Read Your Property Tax Bill for accuracy, assessed value, and any exemptions applied. If something seems off, question it.
- Appeal Assessments: If you believe your property's assessed value is too high, you have the right to appeal. A successful appeal can lower your property tax bill, making it more manageable. Understanding How to Appeal Property Taxes: Complete Guide is a valuable skill for any homeowner.
Seeking Assistance: Payment Plans and Deferrals
If you find yourself struggling to pay your property taxes, don't despair or ignore the problem. Many jurisdictions offer programs designed to help homeowners in temporary or long-term financial distress.
- Payment Plans: Most county tax offices are willing to work with homeowners on setting up installment payment plans for delinquent taxes. This allows you to pay off your debt over several months, rather than needing a large lump sum. While interest and penalties may still apply, it can prevent the escalation to a tax lien sale or foreclosure. Contact your local tax assessor's office directly to inquire about Property Tax Payment Plans: How to Set One Up.
- Deferral Programs: Some states offer property tax deferral programs, particularly for seniors, disabled homeowners, or those with very low incomes. These programs allow eligible homeowners to postpone paying their property taxes until a later date, often until the property is sold or transferred. The deferred taxes typically accrue interest, but it's a way to maintain homeownership during periods of hardship. Explore options like Property Tax Deferral Programs by State to see if you qualify.
- Exemptions and Relief: Make sure you are taking advantage of all available property tax exemptions. Homestead exemptions, senior exemptions, veteran exemptions, and disability exemptions can significantly reduce your tax burden. Many people miss out on these simply because they don't know they exist or how to apply. Our comprehensive guide on Homestead Exemption: Complete State-by-State Guide is an excellent resource.
Financial Tools and Resources
Managing your property's finances, including property taxes, is crucial for long-term homeownership stability. Various tools and services can help you stay organized and plan ahead.
For general financial planning and exploring options for managing debt or securing funds, resources like LendingTree offer a wide range of loan products and financial advice. While not specifically focused on property tax relief, understanding your overall financial picture can help you make informed decisions when unexpected expenses like delinquent taxes arise.
For property owners, especially those with investment properties, platforms like Stessa can be incredibly helpful. Stessa provides tools for tracking income and expenses, including property tax payments, which gives you a clear overview of your property's financial performance. Having organized records can be a lifesaver if you ever need to challenge an assessment or apply for financial assistance.
Ultimately, preventing tax lien foreclosure comes down to awareness, proactive management, and knowing where to turn for help. By staying informed, budgeting diligently, and utilizing available resources, you can protect your home and ensure its long-term financial stability.
Disclaimer
The information provided in this guide is for general informational purposes only and does not constitute legal, financial, or tax advice. Property tax laws are complex and vary significantly by state and local jurisdiction. It is highly recommended to consult with a qualified legal professional, financial advisor, or local tax authority for advice specific to your individual situation. Reliance on any information in this guide is solely at your own risk.