Manufactured Home: Real Property vs Personal Property Tax
It's a common head-scratcher for manufactured home owners: how exactly is your home taxed? This isn't just an abstract question; it directly impacts your annual expenses, how you sell your home, and even how you might finance it. This guide is here to untangle the often-confusing world of manufactured home property taxes, breaking down the critical differences between real property and personal property taxation so you can confidently navigate your ownership journey.
Understanding the Manufactured Home Tax Conundrum
When it comes to property taxes, manufactured homes occupy a unique and often ambiguous space in the eyes of local tax authorities. Unlike a traditional stick-built house that is almost universally classified as real property, a manufactured home can sometimes be treated more like a large vehicle or a piece of movable equipment. This dual nature is the source of much confusion and frustration for homeowners, who often aren't clear on which rules apply to their specific situation until a tax bill arrives. The classification isn't arbitrary; it stems from the home's original construction and how it's ultimately situated on the land.
The Core Distinction: Real vs. Personal Property
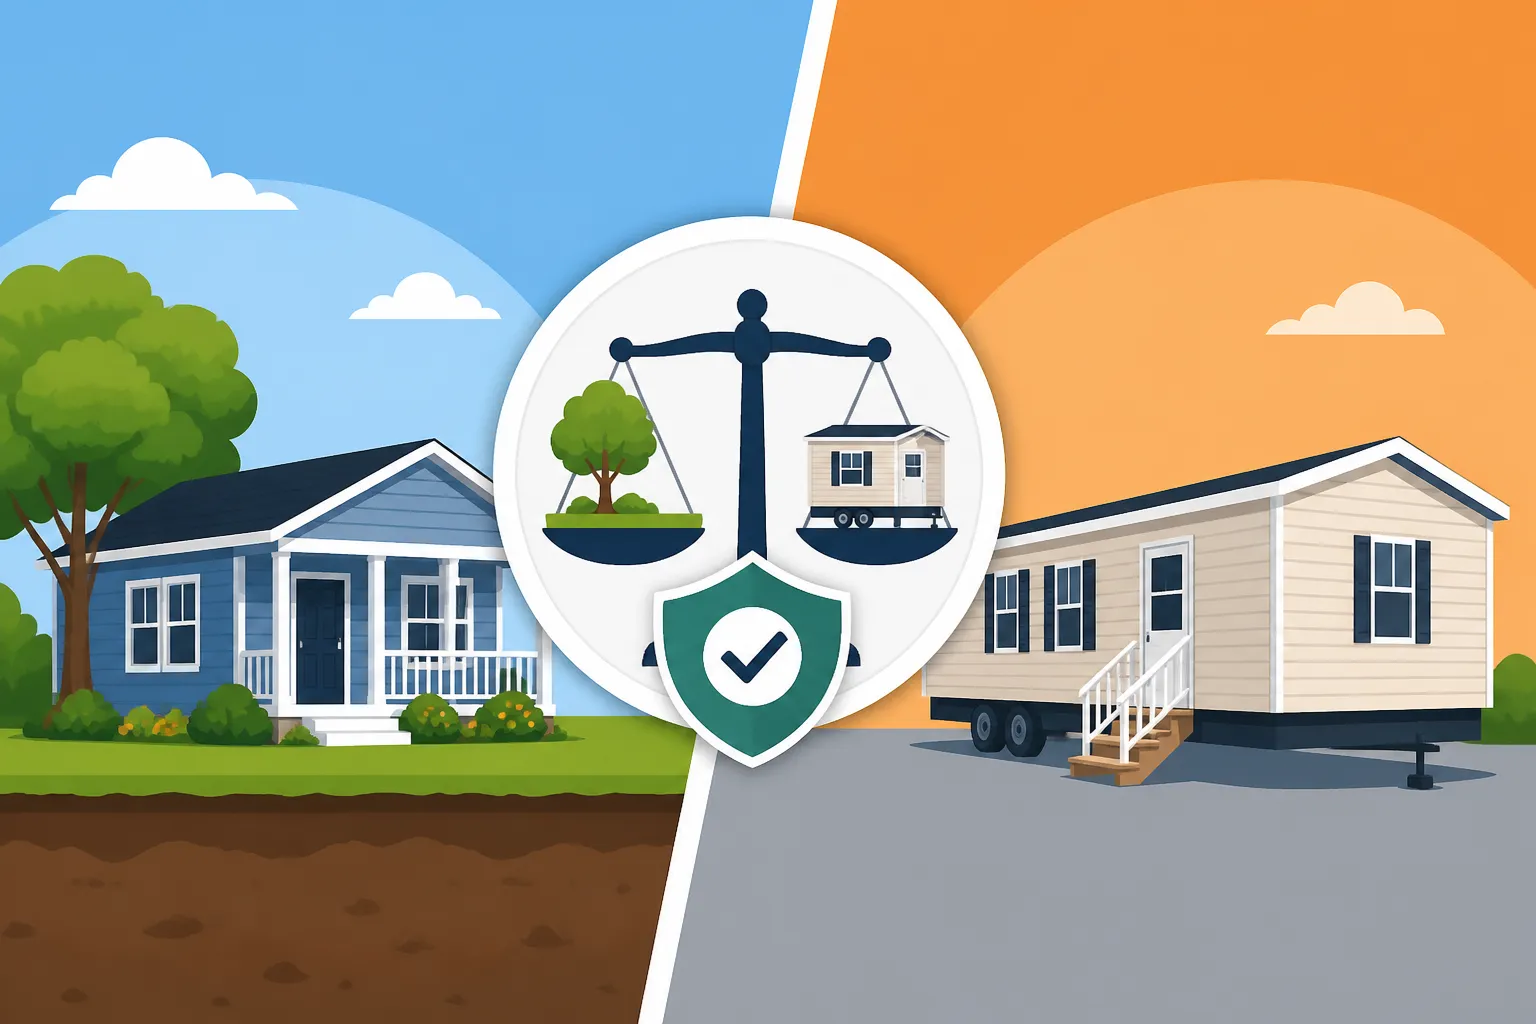
At its heart, the difference between real property and personal property tax for a manufactured home boils down to whether the home is considered "attached" to the land permanently or if it retains its "mobility." Real property, also known as real estate, refers to land and anything permanently affixed to it, including buildings. When a manufactured home is classified as real property, it's assessed and taxed much like any other house on a foundation. This usually means it's treated as part of the land it sits on, contributing to a combined property value.
On the other hand, personal property is movable property not permanently attached to real estate. For manufactured homes, this classification typically applies when the home is still considered "mobile," perhaps because it's situated on leased land, lacks a permanent foundation, or hasn't had its vehicle title retired. In such cases, the home is taxed separately from the land and often subject to different assessment methods and tax rates, sometimes even handled by a different government department than traditional real estate taxes. Understanding this fundamental difference is the first step toward decoding your tax obligations.
Why This Distinction Matters So Much to Your Wallet
The way your manufactured home is classified for tax purposes has profound financial implications that ripple through almost every aspect of homeownership. First and foremost, it affects the amount of tax you'll pay and how frequently you pay it. Real property taxes are generally assessed annually, based on the property's assessed value, which can include both the land and the structure. These taxes often contribute to local services like schools, libraries, and infrastructure, as discussed in detail in our guide on What Is Property Tax Used For?.
When a manufactured home is taxed as personal property, it might be subject to annual registration fees, specific personal property taxes, or even sales tax on its purchase, rather than traditional real estate property taxes. These payments might be due at different times of the year and could have different calculation methods entirely. Beyond the direct tax bill, the classification impacts financing options, potential for appreciation, and ease of resale. Lenders often prefer to finance homes classified as real property because they provide more secure collateral, and real property generally appreciates more reliably than personal property. Without this distinction, you might find yourself facing unexpected costs or limitations.
When a Manufactured Home is Taxed as Real Property
For many manufactured home owners, the goal is often to have their home recognized as real property. This classification typically brings with it the stability and benefits associated with traditional homeownership, including eligibility for conventional mortgages and the potential for long-term value appreciation. However, achieving this status isn't automatic and involves specific actions and compliance with local regulations. It's a journey from a "mobile" classification to one that's firmly rooted in the real estate landscape.
The Permanent Foundation Requirement
The most crucial factor in converting a manufactured home from personal to real property is its installation on a permanent foundation. This isn't just about setting it on some blocks; it involves specific construction standards designed to ensure the home is permanently affixed to the land and meets local building codes. A permanent foundation typically means a concrete slab, a perimeter concrete block foundation, or a system of piers and anchoring devices that are engineered to withstand environmental forces and meet HUD (Housing and Urban Development) standards for manufactured housing. These standards ensure the home is no longer readily movable.
Many states require that the home's wheels, axles, and towing hitch be removed once it's set on this foundation, further cementing its permanent status. Local building departments often need to inspect and approve the foundation work, issuing certificates of occupancy or compliance. Without meeting these stringent requirements, even if your home is stationary, it might not qualify for real property classification, leaving you in the personal property tax camp. It's vital to check with your specific county or municipal planning department for their exact definitions and inspection processes.
Titling and De-Titling Procedures
Another cornerstone of real property classification for manufactured homes is the legal process of "de-titling" or "converting" the home's title. When a manufactured home is first built, it's issued a vehicle title, similar to a car or an RV, by the state's Department of Motor Vehicles (DMV) or equivalent agency. To become real property, this vehicle title must be surrendered or "retired," and the home's ownership must be merged with the land's deed. This is a crucial administrative step that legally binds the home to the real estate.
The de-titling process varies significantly by state but generally involves submitting an application, the original manufactured home title, proof of ownership of the land, and a sworn affidavit confirming the home is permanently affixed to the foundation. Any existing liens on the manufactured home must also be released or transferred to the real property. Once approved, the local county recorder's office will typically record the new status, often issuing a "statement of ownership" or endorsing the property deed to reflect the manufactured home as part of the real property. This step is essential because, without it, even a home on a permanent foundation might still be legally considered personal property, leading to continued personal property taxation.
Impact on Mortgages and Financing
The classification of your manufactured home profoundly impacts your ability to secure conventional mortgages and favorable financing terms. If your manufactured home is still considered personal property, financing options are often limited to chattel loans, which are personal property loans. These loans typically come with higher interest rates, shorter repayment terms, and require larger down payments compared to traditional real estate mortgages. This is because the home isn't secured by the land, making it a riskier asset for lenders.
However, once a manufactured home has been properly affixed to a permanent foundation and de-titled, officially becoming real property, it qualifies for the same types of mortgages available for site-built homes. This includes FHA, VA, USDA, and conventional loans, which offer more competitive rates, longer terms (up to 30 years), and lower down payment requirements. This transition not only makes homeownership more affordable but also simplifies the buying and selling process, as the home and land can be transferred as a single unit, just like any other house. It’s a significant financial advantage that can greatly reduce your overall housing costs.
When a Manufactured Home is Taxed as Personal Property
While many strive for real property status, a significant number of manufactured homes are, and remain, classified as personal property. This doesn't necessarily mean lesser ownership; it simply means a different set of rules and tax implications. Understanding these differences is key to managing your finances effectively, whether you choose this classification or it's simply the reality of your situation. This approach to taxation has its own distinct administrative and financial landscape.
The "Mobile" Aspect and Lack of Permanence
A manufactured home is most commonly taxed as personal property when it retains its "mobile" characteristics and isn't permanently affixed to the land. This often occurs when the home is situated on leased land, such as in a manufactured home park or community. In these scenarios, the homeowner owns the home, but not the land beneath it. Since the home could theoretically be moved, even if that's an unlikely or expensive prospect, it’s not considered a permanent fixture of the real estate.
Even if a manufactured home is on land owned by the homeowner, it might still be classified as personal property if it lacks a compliant permanent foundation or if the vehicle title hasn't been officially surrendered. The presence of wheels, axles, or a towing hitch, or even just the potential for mobility, can lead tax assessors to classify it as personal property. This classification directly influences how your local government, whether it's the county or city, perceives and assesses your home for tax purposes, often separating it entirely from traditional real estate taxation.
Annual Registration and Licensing Fees
For manufactured homes classified as personal property, instead of receiving a traditional real property tax bill, owners typically face a different set of recurring charges: annual registration and licensing fees. These fees are usually administered by the state's Department of Motor Vehicles (DMV) or a similar agency, much like how you register a car or an RV. The amount of these fees can vary widely depending on the home's age, size, and original sales price.
These annual fees can feel like a "car tax" because they often function similarly, renewing each year to keep the home legally permitted to reside in its location. In addition to registration, some jurisdictions may also levy a specific personal property tax on the manufactured home's depreciated value, similar to how boats or airplanes are taxed. These costs are distinct from any property taxes paid on the land itself (if you own it) or lot rent (if you lease). It's crucial for owners to understand these recurring costs and their due dates to avoid penalties, which can be different from those for delinquent real estate taxes. Our guide on Personal Property Tax: Business Equipment & Vehicle 'Car Tax' further explores this concept.
Implications for Resale and Appreciating Value
The personal property classification can significantly impact the resale value and marketability of a manufactured home, particularly in terms of appreciation. Homes classified as personal property often do not appreciate in value at the same rate as real property. In fact, like vehicles, they may tend to depreciate over time, especially older models. This is partly due to financing limitations; chattel loans are less attractive to buyers, which can narrow the pool of potential purchasers and make the sales process more complex.
When selling a personal property manufactured home, the transaction might be more akin to selling a large vehicle than a house. It typically involves transferring the vehicle title, rather than a traditional real estate deed. This can sometimes lead to lower sale prices and fewer opportunities for homeowners to build equity. Buyers also often face the hurdle of finding land to place the home on, or securing a spot in a manufactured home community, adding another layer of complexity. For those considering a manufactured home as a long-term investment, the personal property classification is a crucial factor to weigh, as it directly influences your financial trajectory.
State-by-State Variations in Manufactured Home Taxation
The landscape of manufactured home taxation is anything but uniform across the United States. Each state, and sometimes even individual counties within a state, can have its own specific rules, definitions, and processes for classifying and taxing these homes. What might be considered real property in Florida could still be personal property in Texas, or vice-versa, depending on how it's installed and titled. This patchwork of regulations is a significant reason why many manufactured home owners feel confused and overwhelmed.
Common State Approaches and Classifications
Despite the variations, states generally adopt one of a few common approaches to manufactured home taxation. Some states, like California and Michigan, have historically treated manufactured homes as personal property unless a specific conversion process is completed, often involving permanent affixation and de-titling. Even then, the assessment might differ from site-built homes. Other states, particularly in the Southeast, tend to lean more towards real property classification if certain conditions, primarily a permanent foundation, are met.
Then there are states that offer a choice or have nuanced hybrid systems. For example, a manufactured home on owned land might be eligible for real property classification, while the same home on leased land would remain personal property. The intent behind these regulations is often to distinguish between truly mobile units and those intended to be permanent residences, but the implementation can be quite intricate. Navigating this requires a deep understanding of your local rules, and often a chat with your county assessor's office.
Examples of States with Specific Rules
Let's dive into a few examples to illustrate this complexity.
In Texas, manufactured homes are initially issued a "Statement of Ownership and Location" by the Texas Department of Housing and Community Affairs (TDHCA), similar to a vehicle title. For the home to be taxed as real property, it must be permanently affixed to real estate owned by the homeowner, and the owner must file a "Statement of Attachment" with the county property records. Once that's done, the manufactured home is assessed and taxed as part of the real property, similar to other homes, and can qualify for exemptions like the Texas Homestead Exemption Explained. If these steps aren't taken, or if the home is on leased land, it remains personal property and is subject to different taxation by the county.
Florida has a slightly different approach. Manufactured homes are typically classified as tangible personal property by default, requiring annual registration. However, they can be converted to real property if they are permanently affixed to land owned by the homeowner and the homeowner files a "Declaration of Domicile" with the clerk of the circuit court, effectively retiring the vehicle title. Once converted, they are assessed by the county property appraiser as real estate. This conversion is crucial for qualifying for the Florida Homestead Exemption (March 1 Deadline), which can significantly reduce your tax burden.
In California, prior to Proposition 19, manufactured homes were largely treated as personal property unless they were installed on a foundation system in compliance with local building codes, had a "Notice of Abatement" recorded, and had the vehicle registration purged. This meant separate assessments and tax bills for the home and the land. With the changes brought by Prop 19, there are new considerations, especially for inherited properties. Generally, if the home is on a permanent foundation and the land is owned, it’s often assessed as real property, but the process of de-titling and integration into the real property assessment roll is paramount. If a manufactured home is still considered personal property, it may be subject to vehicle license fees and local personal property taxes.
These examples highlight that simply owning a manufactured home doesn't dictate its tax status; rather, it's a combination of physical installation, legal titling, and specific state and local regulations that make all the difference. Always confirm the current rules with your local appraisal district or assessor's office.
Managing Your Manufactured Home Property Taxes
No matter how your manufactured home is classified, managing your property taxes effectively is a critical part of being a responsible homeowner. This involves not only understanding your current status but also exploring ways to potentially reduce your tax burden and keeping meticulous records of all related financial transactions. Staying organized can save you headaches and money down the road.
How to Determine Your Home's Classification
The first and most important step in managing your manufactured home taxes is to definitively determine whether your home is classified as real property or personal property in your specific jurisdiction. Don't rely on assumptions or what a previous owner told you; tax laws change, and interpretations can vary. Start by looking at your current tax bills. Do you receive a traditional property tax bill that includes both the land and the structure, typically from the county tax assessor's office? Or do you receive separate bills, perhaps one for the land and another for "tangible personal property" or a vehicle registration notice from the DMV? The entity sending the bill is often a big clue.
Next, check your official documentation. Do you have a recorded deed that explicitly includes the manufactured home as part of the real estate, or do you still possess a manufactured home vehicle title? A quick call or visit to your county's appraisal district, tax assessor's office, or Department of Housing can provide clarity. Be prepared with your property's address, parcel number, and any VIN or serial numbers for your manufactured home. They can tell you how your home is currently classified and what steps, if any, would be required to change that classification. This proactive research is vital, especially if you're considering buying or selling.
Strategies for Lowering Your Tax Burden
Once you understand your home's tax classification, you can explore strategies to potentially lower your tax burden. If your manufactured home is classified as real property, you should investigate all available property tax exemptions. Common exemptions include the homestead exemption for primary residences, senior citizen exemptions, veteran exemptions, and disability exemptions. These can significantly reduce your taxable value. For example, many states offer a homestead exemption that reduces the assessed value of your primary residence, leading to a lower tax bill. Check out our guide on Homestead Exemption: Complete State-by-State Guide to see what's available in your state.
Additionally, if you believe your manufactured home's assessed value is too high, you have the right to appeal your property tax assessment. This process usually involves gathering evidence, such as comparable sales of similar manufactured homes in your area, and presenting it to your local appraisal review board. Even if your home is personal property, some jurisdictions allow for appeals of personal property tax assessments if you can demonstrate an overvaluation. Keeping good records of any improvements or damages can also help you argue for a more accurate assessment.
Tools and Resources for Tracking Your Property Finances
Managing a manufactured home, regardless of its tax classification, requires diligent financial tracking. You need to keep tabs on your property tax payments, insurance premiums, maintenance costs, and any rental income or lot fees. This is where modern property management tools can be incredibly helpful. Platforms like Stessa, for example, are designed to help property owners organize their finances, track expenses, and monitor cash flow for single properties or entire portfolios.
Using a tool like Stessa can make it much easier to prepare for tax season, whether you're dealing with real property taxes or personal property fees. You can upload and categorize receipts, track your property tax bills, and generate reports that show your financial performance. This kind of organized data is invaluable, not just for tax purposes but also for understanding the true cost of ownership and making informed financial decisions. Having a clear picture of your income and expenses can also be extremely beneficial if you ever decide to protest your property tax assessment, as you'll have all your financial information readily accessible. Furthermore, understanding your overall expenses can help you budget more effectively, ensuring you’re always prepared for those annual or semi-annual tax payments.
| Feature | Manufactured Home (Real Property Tax) | Manufactured Home (Personal Property Tax) |
|---|---|---|
| Legal Status | Considered part of the land; covered by real estate deed | Considered movable property; covered by vehicle title |
| Foundation | Must be permanently affixed to a permanent foundation | Often on a non-permanent foundation or rented land |
| Tax Assessment | Assessed annually by county assessor (land + home) | Assessed annually (or periodically) as personal property by DMV/tax office |
| Tax Basis | Based on market value of home and land | Based on depreciated value of the home only |
| Payment Frequency | Typically annual or semi-annual | Often annual registration/licensing fees, sometimes specific personal property tax |
| Financing | Eligible for traditional mortgages (FHA, VA, Conventional) | Typically limited to chattel loans (higher rates, shorter terms) |
| Appreciation | Potential for similar appreciation as site-built homes | Tends to depreciate like vehicles, less investment potential |
| Transfer of Ownership | Real estate closing, deed transfer | Title transfer, like a vehicle |
| Exemptions | Eligible for homestead, senior, veteran exemptions (if applicable) | Generally fewer tax exemptions directly on the home itself (may apply to land if owned) |
Disclaimer
The information provided in this article is for general informational purposes only and does not constitute financial, tax, or legal advice. Property tax laws and regulations are complex and vary significantly by state, county, and municipality. We strongly recommend consulting with a qualified tax professional, real estate attorney, or your local tax assessment office for advice tailored to your specific situation.