What Is PITI in a Mortgage Payment?
For many homeowners, that monthly mortgage statement can feel like a black box, a single number that magically appears, often shifting without clear explanation. It's easy to get lost in the jargon, but understanding the true components of your housing payment is crucial for financial peace of mind. This guide will meticulously break down PITI – Principal, Interest, Taxes, and Insurance – giving you a clear, comprehensive understanding of where your money goes each month.
Deconstructing Your Monthly Mortgage Payment: The PITI Breakdown
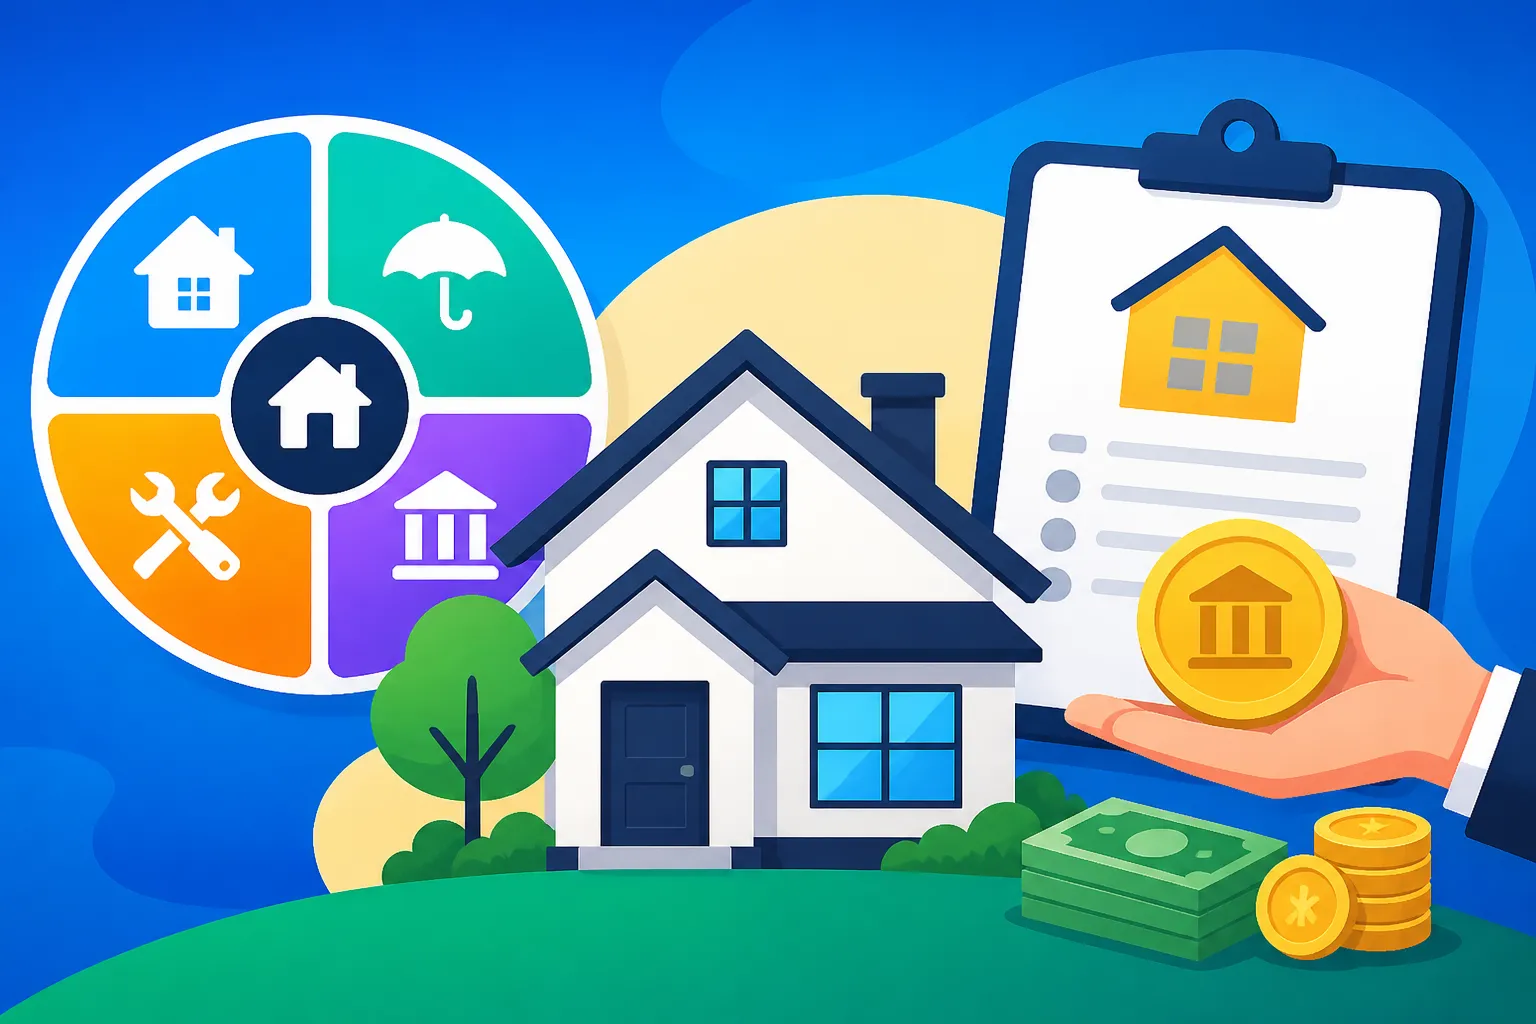
When you receive your mortgage statement, the total amount you owe isn't just about paying back the money you borrowed. It’s a carefully bundled sum that includes four key elements, commonly referred to by the acronym PITI: Principal, Interest, Taxes, and Insurance. Each component plays a vital role in your homeownership journey, and understanding them individually is the first step to truly managing your finances.
Principal: The Heart of Your Loan Repayment
The principal is arguably the most straightforward part of PITI: it's the actual dollar amount you borrowed from the lender to purchase your home. Think of it as the real chunk of money that reduces the outstanding balance of your loan. Every single principal payment you make brings you closer to outright owning your home.
When you first start paying your mortgage, especially in the early years of a 15-year or 30-year loan, a surprisingly small portion of your payment often goes towards principal. This is due to a process called amortization. Lenders structure loans so that a larger share of your early payments covers the interest, which is their profit. As time goes on and your loan balance decreases, a greater percentage of your fixed monthly payment starts to chip away at the principal. For instance, if you have a $300,000 mortgage, your first payment might see only $300 go to principal, while $1,200 goes to interest. Fast forward 15 years, and that ratio could be completely flipped, with more going to principal and less to interest. This dynamic is why some homeowners consider making extra principal payments, even small ones, in the early stages; it can significantly reduce the total interest paid over the life of the loan and shorten the repayment period.
Interest: The Cost of Borrowing
Interest is essentially the fee your lender charges you for the privilege of borrowing their money. It's how financial institutions like banks and mortgage companies make a profit, and it's calculated as a percentage of your remaining loan balance. The interest rate you secure when you take out your mortgage is critical, as it directly impacts your monthly payment and the total cost of your home over time.
Interest rates are influenced by a multitude of factors, including the prevailing market rates, economic conditions, the specific type of loan you choose (fixed-rate vs. adjustable-rate), and your own financial profile, particularly your credit score. A higher credit score typically translates to a lower interest rate, saving you tens of thousands of dollars over the life of a loan. Let's say you're looking at a $300,000 mortgage. A 6% interest rate will result in a significantly higher monthly interest payment than a 5% rate, and that difference compounds over years. Shopping around for the best rate is essential, and platforms like LendingTree can be incredibly helpful for comparing offers from various lenders without having to contact each one individually. Always remember that interest is calculated on your outstanding principal balance, so as you pay down the principal, the amount of interest you owe each month naturally decreases.
Taxes: The Property Tax Component
This is where things can get a little less straightforward than principal and interest, but it's equally crucial. The "T" in PITI stands for property taxes, which are local taxes assessed by your state, county, and sometimes even specific municipalities or school districts. These taxes fund essential public services like schools, libraries, police and fire departments, and local infrastructure improvements. Unlike principal and interest, which go to your lender, property taxes go to these various local government entities.
Most mortgage lenders require homeowners to pay their property taxes through an escrow account. This means a portion of your estimated annual property tax bill is collected with your monthly mortgage payment and held by the lender in a special account. When the tax bills come due – often annually or semi-annually – your lender uses the funds in your escrow account to pay them on your behalf. This system ensures that taxes are paid on time, protecting the lender's investment (as unpaid property taxes can lead to tax liens and even foreclosure). The amount of property tax you pay depends on two main factors: your home's Assessed Value vs Market Value vs Taxable Value and the local tax rate, often expressed as a What Is a Mill Rate? (Millage Explained). Because property values and tax rates can change, your property tax payment, and thus your overall PITI, can fluctuate from year to year. For a deeper dive into how these figures are determined, you might want to read our guide on How Are Property Taxes Calculated?. It’s common for homeowners to see their PITI payments adjust due to changes in these local levies.
Insurance: Protecting Your Investment
The final "I" in PITI stands for insurance, and it typically encompasses two main types: homeowner's insurance and, if applicable, private mortgage insurance (PMI). Homeowner's insurance, also known as hazard insurance, protects your home and personal belongings against damage from covered events like fire, theft, vandalism, and certain natural disasters. It also typically provides liability coverage in case someone is injured on your property. Lenders almost always require you to carry homeowner's insurance to protect their financial interest in the property. Without it, if your home were destroyed, there would be no collateral for their loan.
Similar to property taxes, homeowner's insurance premiums are usually collected monthly through your escrow account. The lender pays the annual premium directly to your insurance provider when it's due. The cost of homeowner's insurance varies widely based on factors like your home's location, age, construction type, claim history, and the coverage limits you choose. In areas prone to specific risks, like coastal regions susceptible to hurricanes or flood zones, you might also be required to carry additional insurance, such as flood insurance, which is typically not covered by standard homeowner's policies. Then there's Private Mortgage Insurance (PMI). If you put down less than 20% of the home's purchase price, most conventional lenders will require you to pay PMI. This protects the lender, not you, in case you default on your loan. Once you build up sufficient equity (usually 20-22%), you can often request to have PMI removed, which can reduce your monthly PITI payment.
Why PITI Matters More Than Just "Mortgage"
Understanding PITI isn't just about knowing acronyms; it's about grasping the full financial commitment of homeownership. Simply looking at the principal and interest portion of your loan gives you an incomplete picture, potentially leading to budgeting miscalculations and unpleasant surprises down the road.
Understanding Your True Monthly Housing Cost
When you're approved for a mortgage, the lender doesn't just evaluate your ability to pay back the loan amount itself. They consider your capacity to handle the entire PITI payment, because that's your actual monthly housing expense. This comprehensive view ensures that you're prepared for all the ongoing costs associated with owning a home, not just the debt repayment. Many first-time homebuyers, in particular, often focus solely on the principal and interest portion, only to be surprised by the additional burden of taxes and insurance.
For example, imagine two homes, both with a $300,000 principal and interest payment. One is in a state with low property taxes and affordable insurance, resulting in a PITI of $2,000. The other is in a high-tax state with costly insurance, pushing the PITI to $3,500. While the loan amount is the same, the true cost of living in each home is vastly different. This is why when you're house hunting, you need to factor in the total PITI, not just what the bank tells you the loan amount will be. It gives you a much more realistic budget to work with and helps avoid the financial strain that comes from underestimating your monthly obligations. For those managing multiple properties or looking for detailed expense tracking, tools like Stessa can provide invaluable insights by consolidating all PITI components and other property-related financials in one place, helping you see the full cost picture.
The Role of Escrow Accounts
Escrow accounts are the unsung heroes of the PITI system for many homeowners. They streamline the payment of your property taxes and insurance premiums, ensuring these critical bills are paid on time and preventing you from having to save up large lump sums yourself. Most lenders mandate an escrow account to safeguard their investment; they don't want you to default on your taxes or insurance, as it puts their collateral (your home) at risk. For a detailed explanation, check out our guide on Escrow & Impound Accounts Explained.
Here's how it works: each month, a portion of your PITI payment is deposited into this separate escrow account, managed by your mortgage servicer. The servicer then pays your property tax bills (which can be annual or semi-annual, depending on your location and the local taxing authority) and your homeowner's insurance premiums (usually annual) directly from this account when they become due. This offers a significant convenience, as you don't have to worry about missing deadlines or coming up with large payments several times a year. However, it also means you lose direct control over those funds until they are disbursed. Sometimes, you might encounter an "escrow shortage" if the estimated amount collected wasn't enough to cover rising taxes or insurance. This will lead to an increase in your monthly PITI payment the following year. Understanding how this process works, from the initial setup to annual analyses, is crucial for financial preparedness.
| PITI Component | Description | Recipient | Typical Frequency of Change | Impact on Payment |
|---|---|---|---|---|
| Principal | Portion of payment reducing the actual loan balance. | Mortgage Lender | Decreases over loan term | Predictable |
| Interest | Cost of borrowing money, calculated on outstanding principal. | Mortgage Lender | Decreases over loan term | Predictable |
| Taxes | Property taxes paid to local government entities. | Local Taxing Authorities | Annually/Bi-annually | Can fluctuate |
| Insurance | Homeowner's insurance, PMI, flood insurance premiums. | Insurance Carriers/Lender | Annually | Can fluctuate |
Fluctuations in Your PITI Payment and How to Prepare
One of the most common frustrations homeowners face is when their monthly PITI payment changes unexpectedly. While the principal and interest portions of a fixed-rate mortgage remain consistent, the "T" and "I" are anything but. These fluctuations can throw off a carefully planned budget, making it feel like you're constantly chasing a moving target.
Common Causes for PITI Changes
The primary culprits behind a changing PITI payment are increases in property taxes and insurance premiums. Let's start with taxes. Local tax assessors periodically reassess property values to reflect market conditions. If your home's assessed value goes up, and the local Property Tax Assessment Ratio by State and What Is a Mill Rate? (Millage Explained) remain the same or increase, your tax bill will naturally climb. This is a common occurrence in appreciating housing markets. Additionally, local governments might increase their overall tax rates (the millage rate) to fund new initiatives or address budget shortfalls, impacting everyone in the taxing district. You can often find information on your state's property tax rates, such as the Florida Property Tax Rate Explained or Texas Property Tax Rate Explained, and How Often Is Property Reassessed?. An unexpected jump in your property taxes can easily lead to your mortgage servicer adjusting your escrow payment to ensure enough funds are collected to cover the new, higher bill. If you're wondering Why Did My Property Taxes Go Up?, understanding these assessment and rate changes is key.
Insurance premiums are another major variable. Factors like widespread natural disasters (e.g., hurricanes in Florida, wildfires in California), inflation driving up repair costs, or even your individual claims history can cause your homeowner's insurance rates to increase significantly. Insurance companies analyze risk constantly, and if the perceived risk for your area or property goes up, so will your premiums. When your insurance provider notifies your lender of a premium increase, your mortgage servicer will then adjust your monthly escrow collection to ensure they're gathering enough to cover the new annual premium. This is a normal part of the process, but it can still be jarring when you see your monthly payment jump.
Proactive Strategies for Managing PITI
While some changes to your property taxes and insurance are beyond your control, there are definitely proactive steps you can take to manage and even mitigate these increases. First and foremost, pay close attention to your annual property tax assessment notices. If you believe your home's assessed value is higher than its true market value, or if it's disproportionately higher than comparable homes in your area, you have the right to appeal. Our guide on How to Appeal Property Taxes: Complete Guide provides a detailed roadmap for this process, including how to gather evidence and meet deadlines, such as the Texas Property Tax Protest Deadline & ARB Process. Even if you don't appeal every year, it's wise to review the assessment carefully. Remember, Property Tax Assessment Caps (Prop 13, Save Our Homes, Texas 10%) exist in some states, which can provide a degree of protection against dramatic increases.
Secondly, don't be afraid to shop around for homeowner's insurance periodically. Your loyalty might not always be rewarded with the best rates. Get quotes from different insurance providers every few years to ensure you're getting competitive coverage for your money. You might find significant savings by switching carriers without sacrificing crucial protection. Lastly, it’s always a good idea to maintain a financial cushion in an emergency fund specifically for potential escrow shortages. If your taxes or insurance suddenly jump, having those extra funds available can prevent a scramble or a steep increase in your monthly PITI. Make sure you know How to Read Your Property Tax Bill and your annual escrow analysis statement, which your mortgage servicer sends out, to stay informed about these potential changes.
Disclaimer
Please note that this content is intended for informational purposes only and does not constitute financial, legal, or tax advice. Property tax laws, insurance regulations, and mortgage terms are complex and can vary significantly by state, county, and individual circumstances. We strongly recommend consulting with a qualified financial advisor, tax professional, or real estate expert for personalized advice regarding your specific situation.